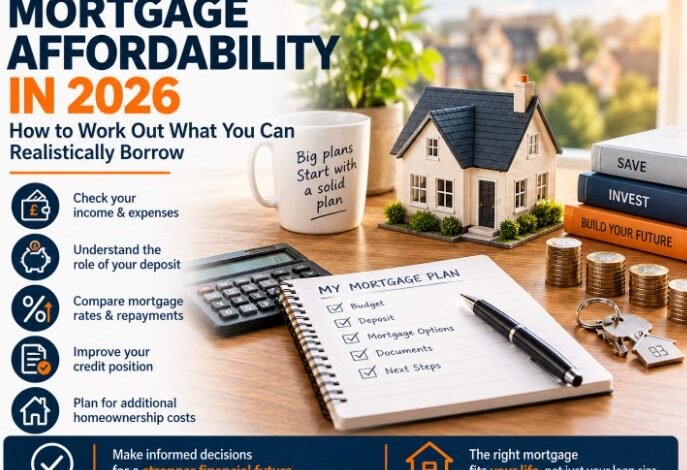
Mortgage Affordability in 2026: How to Work Out What You Can Realistically Borrow

Getting a mortgage is not simply a question of meeting a lender’s minimum income requirement. A successful application depends on the relationship between income, expenditure, existing financial commitments, deposit size and the lender’s criteria. Equally important is whether the repayments remain manageable for the household after the mortgage completes.
In 2026, borrowers need to pay particular attention to affordability because mortgage pricing has been volatile and everyday household costs remain an important part of financial planning. Understanding how affordability works can help buyers set a realistic budget before searching for a property.
What Does Mortgage Affordability Mean?
Mortgage affordability refers to whether a borrower can reasonably maintain the required repayments alongside other financial commitments.
Lenders consider income and regular expenses to estimate the amount a household may be able to borrow. They may also examine employment stability, credit history, dependants, existing loans and the proposed mortgage term.
A lender’s maximum offer is not necessarily the amount you should borrow. Your personal budget may need to be more conservative, particularly if you have irregular income, expect changes in household circumstances or want to maintain substantial savings.
The objective is to find a mortgage that supports homeownership without leaving too little money for other essential needs.
How Income Affects Borrowing Capacity
Income is an important starting point, but lenders do not all treat every type of income identically.
For employees, basic salary may be supported by payslips and bank statements. Overtime, bonuses and commission may be assessed according to their consistency and the lender’s policy.
Self-employed applicants may need to provide tax calculations, tax-year overviews and business accounts. Contractors and company directors may have different documentation requirements depending on how they receive their income.
Some lenders use income multiples as part of their assessment. MoneyHelper notes that four and a half times annual income is a common upper reference point, but many borrowers are offered less. It is not a universal entitlement or a guarantee of borrowing capacity.
A lender must consider the overall application and its own criteria. Applicants should therefore avoid setting a property budget solely by multiplying their salary by a fixed number.
Why Monthly Expenses Matter
Two households with identical incomes can have very different borrowing capacity because their regular expenses differ.
Lenders may consider credit cards, personal loans, car finance, childcare, school fees, transport costs and other commitments. They may also assess household bills and regular spending to understand the amount available for mortgage payments.
Before applying, create a realistic monthly budget. Include rent, utilities, food, travel, subscriptions, insurance and any financial support you provide to other people.
Do not underestimate expenses to make a mortgage appear affordable. If the budget only works when you ignore occasional costs or assume that nothing unexpected will happen, the borrowing may be too high.
Review the budget against your actual bank statements over several months. This can help reveal spending patterns that are easy to overlook.
The Role of Your Deposit
A deposit reduces the amount you need to borrow. The relationship between the mortgage and the property’s value is called the loan-to-value ratio, or LTV.
For example, if a property costs £250,000 and you provide a £25,000 deposit, you need to borrow £225,000. The mortgage has an LTV of 90%.
A larger deposit can sometimes provide access to a broader selection of mortgage products and lower interest rates. However, using every available pound as a deposit may leave you without enough money for legal fees, moving costs, repairs and emergencies.
The best approach is to balance the deposit against the need for financial resilience after completion.
Understand Mortgage Rates and Repayments
The interest rate affects monthly payments and the overall cost of borrowing.
As of September 2026, the Bank of England’s Bank Rate stood at 3.75%. Mortgage rates are not identical to Bank Rate, and fixed-rate pricing can change in response to wholesale funding costs and expectations about future policy.
Market reporting in October 2026 showed that fixed mortgage rates had experienced upward pressure. The rate available to an individual borrower will also depend on deposit size, credit profile, product fees, mortgage term and lender criteria.
When comparing mortgages, look at the monthly repayment and the total cost over the period that matters to you. Include product fees and consider what happens when an introductory deal ends.
A longer mortgage term generally reduces the required monthly repayment, all else being equal, but can increase the total interest paid. A shorter term usually increases monthly payments while reducing the period over which interest accumulates.
Use a mortgage calculator to explore scenarios, but remember that a calculator cannot guarantee a lender’s offer.
Stress-Test Your Budget
A useful affordability exercise is to consider what would happen if your circumstances changed.
Could you continue paying the mortgage if interest rates increased when your deal ended? Would the payments remain manageable if one household member temporarily stopped working? Could you cover an unexpected repair or a rise in energy bills without relying on new debt?
Fixed-rate mortgages provide certainty about the interest rate during the agreed period, but they do not eliminate every financial risk. Household costs can rise, and borrowers may face a different rate when they refinance.
Consider maintaining emergency savings where possible. MoneyHelper recommends thinking about how you would manage unexpected changes in income and expenditure when assessing mortgage affordability.
The purpose of stress-testing is not to predict every possible problem. It is to identify a borrowing level that leaves room for realistic changes.
Improve Your Credit Position
Before applying, check your credit reports for incorrect information. Make sure your address details are accurate and that outstanding credit commitments are properly recorded.
Pay bills and credit commitments on time, avoid unnecessary borrowing and reduce expensive unsecured debt where practical. However, avoid making abrupt financial changes without understanding their implications for the application.
A credit score alone does not determine mortgage approval. Lenders use their own assessment criteria, and the wider financial picture matters.
If you have missed payments or previous credit problems, do not assume that every lender will reject you. The nature, severity and age of the issue can affect the options available. Accurate disclosure and appropriate advice are important.
Consider Additional Homeownership Costs
Your affordability assessment should include more than the mortgage payment.
Allow for solicitor fees, surveys, property transaction taxes where applicable, insurance, moving costs, repairs and ongoing maintenance. If you buy a flat, investigate service charges and any other property-related obligations.
Tax rules differ across the UK. England and Northern Ireland use Stamp Duty Land Tax, Scotland uses Land and Buildings Transaction Tax, and Wales uses Land Transaction Tax. Check the rules applicable to your purchase before deciding how much cash you need.
Where Mortgage Advice Fits In
A mortgage adviser can help you understand how lenders may assess your income and commitments, identify potentially suitable products and explain the documentation required. The range of lenders an adviser can consider depends on their market coverage and permissions.
Prestige Mortgage Solutions Ltd provides mortgage-advice services and advertises support for residential buyers, remortgages and applicants with more complex circumstances. When choosing an adviser, ask how fees work, how the adviser is remunerated, what lender range is available and whether the service includes support through the application.
Final Thoughts
Mortgage affordability is about more than securing the largest possible loan. It means finding a balance between the property you want, the deposit you can provide and the repayments you can comfortably manage.
By reviewing your income, tracking expenses, checking your credit history and stress-testing your budget, you can approach the mortgage process with clearer expectations. Careful preparation and suitable advice can help you make a decision that remains manageable beyond completion day.
This article is for general information only and does not constitute mortgage, legal, tax or financial advice. Borrowing capacity and product availability depend on individual circumstances and lender criteria. Your home may be repossessed if you do not keep up repayments on your mortgage.